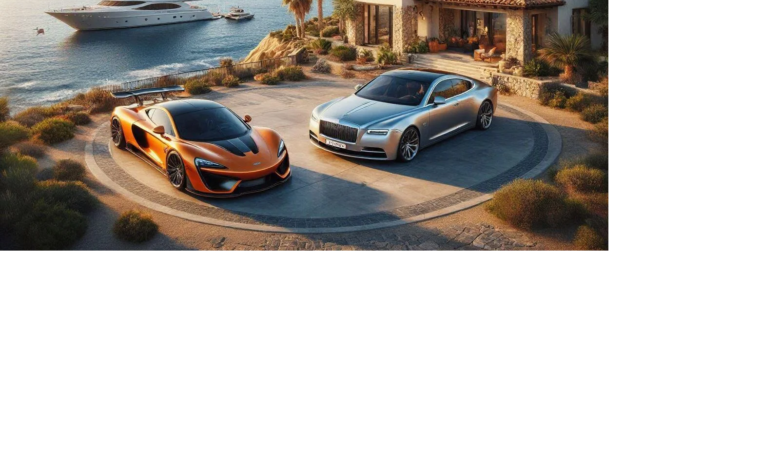
Federal authorities said at least $7.3 million in investor funds supported Bernhard Eugen Fritsch’s personal expenses, including mortgage payments, luxury automobiles, yacht improvements, and renovations to his Malibu residence, rather than developing StarClub’s promised celebrity-marketing technology.
WASHINGTON, DC, September 24, 2026: A McLaren, a Rolls-Royce, an upgraded yacht, and renovations to a mansion near Malibu’s Carbon Beach became defining evidence in the federal prosecution of StarClub founder Bernhard Eugen Fritsch, whose investors were told their money would help build technology for the celebrity economy.
The luxury assets gave prosecutors a vivid way to explain a complicated financial case, translating years of investment transfers, company expenditures, fundraising representations, and internal transactions into recognizable purchases that jurors could compare with Fritsch’s stated plans for developing StarSite.
Federal authorities said the personal spending was not incidental to the case, because it supported their contention that Fritsch obtained millions through false statements about StarClub’s performance and then used substantial investor capital differently from the purposes presented during fundraising.
The FBI’s current profile of Fritsch states that at least $7.3 million in investor money funded personal expenses such as mortgage payments, residential costs, and luxury vehicles after approximately $35 million was raised between January 2014 and August 2017.
Those figures do not mean every dollar StarClub received was spent personally or that every luxury asset necessarily represented criminal proceeds, but they describe the financial diversion theory federal prosecutors successfully presented during a nine-day wire-fraud trial.
Investors Were Funding a Technology Story
StarClub promoted an application called StarSite that was intended to help celebrities and social-media influencers distribute content, deliver advertising to followers, monetize brand endorsements, and share advertising revenue generated through their online audiences.
That business model required substantial development capital because a functioning commercial platform would need software engineers, secure infrastructure, content-management systems, analytics, advertising technology, celebrity recruitment, legal agreements, sales personnel, and ongoing support to serve large fan communities.
Fritsch told investors their money would fund StarClub’s channels, technology, and general corporate purposes, linking new capital to the operational work needed to turn an appealing concept into a scalable business.
Investors accepting early-stage technology risk may tolerate significant losses when money is honestly spent pursuing the proposed strategy, but undisclosed personal use creates a fundamentally different issue because it changes both the company’s resources and the accuracy of the investment decision.
The government’s case therefore focused not simply on whether StarSite achieved commercial success, but on whether Fritsch intentionally misrepresented StarClub’s financial condition, corporate relationships, revenue, prospective deals, and intended use of newly invested funds.
The $7.3 Million Personal-Expense Figure
The FBI now attributes at least $7.3 million in investor money to Fritsch’s personal expenses, a substantial amount representing more than isolated reimbursements or occasional accounting errors within a company that reportedly raised approximately $35 million overall.
That total covered categories including mortgage and residential payments as well as luxury vehicles, according to the bureau, while prosecutors highlighted specific expenditures involving the Malibu property, a yacht, a McLaren, and a Rolls-Royce.
The phrase “at least” matters because it identifies a documented minimum rather than necessarily describing every transaction investigators questioned, while the broader fundraising and restitution figures reflect different measurements serving different purposes in the case.
Approximately $35 million refers to the total amount the FBI says Fritsch raised for StarClub, while the $7.3 million figure addresses identified personal spending and the $26,806,901 restitution order represents the court’s legally determined repayment obligation.
Those amounts should not be merged or treated as interchangeable, because money raised, money diverted, victim loss, asset value, forfeitable property, criminal fines, and restitution each answer distinct financial and legal questions within the prosecution.
The McLaren and Rolls-Royce
Luxury automobiles offered prosecutors easily understood symbols of personal consumption, particularly because a McLaren and Rolls-Royce ordinarily communicate wealth, exclusivity, and discretionary spending rather than the routine transportation needs of a developing software company.
Their evidentiary importance, however, depended upon financial tracing and context rather than appearance alone, because owning an expensive vehicle is lawful and does not establish fraud without proof connecting the purchase to misrepresented or improperly used funds.
Prosecutors presented the cars as part of a larger pattern in which investor capital allegedly flowed into Fritsch’s lifestyle while investors were told their contributions would expand StarClub’s technology, channels, and corporate operations.
That connection allowed the government to argue that the vehicles were not merely evidence of questionable executive judgment, but visible products of a scheme in which the use of proceeds differed materially from the expectations created during fundraising.
Law enforcement later seized both automobiles and placed them into federal forfeiture proceedings to determine whether the government could retain and dispose of the property under laws addressing assets connected with proven criminal conduct.
Yacht Improvements Under Scrutiny
The yacht introduced another form of disputed personal spending because large vessels require costly repairs, marina fees, insurance, maintenance, staffing, registration, and expensive upgrades that continue to consume money long after the original purchase.
Federal summaries state that Fritsch used investor funds to fix up or improve the yacht, giving prosecutors an expenditure that seemed particularly far removed from the technical and commercial work investors believed they were financing.
As with the automobiles, the vessel’s luxury character did not independently prove wire fraud, but tracing investor money into yacht expenses could reinforce the allegation that Fritsch’s representations about corporate use were materially misleading.
The yacht was seized with the McLaren and Rolls-Royce and made subject to forfeiture proceedings, although seizure itself should be distinguished from a final determination resolving ownership, criminal connection, creditor priority, and the government’s ultimate authority to dispose of property.
Even when forfeiture succeeds, a yacht can produce less value than observers expect because maintenance, storage, deterioration, liens, sale expenses, and changing market conditions may reduce the net amount potentially available for lawful distribution.
Renovating the Malibu Residence
The Malibu residence near Carbon Beach gave the government’s narrative a geographic centerpiece, connecting StarClub’s Santa Monica fundraising operation with a highly valuable personal property in one of Southern California’s most recognizable luxury communities.
Prosecutors said investor funds supported renovations to the mansion, while the FBI’s description more broadly identifies mortgage and residential expenses among the categories receiving at least part of the $7.3 million attributed to personal use.
Residential spending can be harder to evaluate than purchasing a sports car because executives may work from home, host business meetings, receive disclosed housing benefits, or incur legitimate expenses that overlap with personal property.
The relevant questions therefore include whose property was improved, whether the company received a documented business benefit, how the payments were recorded, what investors were told, and whether any compensation or related-party arrangement was properly disclosed.
In Fritsch’s case, prosecutors persuaded jurors that the personal spending supported their broader fraud theory, securing a conviction on one wire-fraud count even though the jury acquitted him on a second count submitted during the same trial.
Why Use of Proceeds Matters
An investor’s decision depends not only upon a company’s proposed product and expected return, but also upon management’s explanation of how new capital will be allocated and what controls will protect the enterprise from undisclosed personal extraction.
Money intended for engineering cannot simultaneously pay a personal mortgage without reducing the funds available for product development, while capital spent renovating a private residence cannot finance the same marketing, staffing, licensing, or infrastructure promised in a business plan.
Undisclosed diversion can therefore injure investors twice: first by transferring value to the executive and again by materially weakening the company whose future success was supposed to generate a return on their investment.
Use-of-proceeds statements can also affect risk assessment because investors may contribute additional money when they believe earlier funding has advanced specific milestones, even though personal spending may have prevented those milestones from being reached.
The government presented Fritsch’s expenditures alongside allegedly false claims about StarClub’s revenue, institutional investors, major-media relationships, commercial agreements, investment interest, and possible buyout offers, creating a combined picture rather than relying upon lifestyle evidence alone.
Financial Records Turn Lifestyle Into Evidence
Luxury assets become meaningful financial evidence only when investigators can connect them with dates, accounts, transfers, invoices, ownership records, corporate books, investor communications, and representations made before or during the documented movement of money.
Bank statements can show funds entering a company account and later moving toward a mortgage provider, vehicle dealer, marina, contractor, or related entity, while accounting records may reveal whether the transaction was classified as compensation, a loan, an expense, or something else.
Invoices and property records can then identify what was purchased, who benefited, whether the company retained ownership, and whether the expenditure matched a budget or board authorization, which investigators and jurors can use.
International or offshore banking arrangements do not automatically establish wrongdoing, because lawful cross-border accounts serve many legitimate purposes, but regulated institutions still create compliance records that may matter when authorities have appropriate legal process.
The persuasive force of financial tracing comes from reconstruction rather than spectacle, allowing prosecutors to move beyond photographs of expensive property and demonstrate how money allegedly traveled from investors toward identifiable personal benefits.
Seizure, Forfeiture, and Restitution Are Different
The government’s seizure of the two cars and yacht removed those assets from Fritsch’s immediate control, but it did not automatically transfer their full retail value to victims or satisfy the later restitution judgment the federal court entered.
Seizure is a protective enforcement step, forfeiture determines whether property can legally be taken because of its relationship to an offense, and restitution creates a separate obligation requiring the defendant to compensate eligible victims for court-recognized losses.
Each process may involve different parties, evidentiary standards, formal notices, court hearings, ownership claims, liens, and distribution procedures, meaning a highly publicized seizure can represent only the beginning of a complicated financial recovery process.
Third parties may claim ownership or a superior legal interest, while secured creditors, storage expenses, depreciation, and sale costs can substantially reduce the value remaining after a forfeited item is liquidated.
Fritsch’s restitution obligation of $26,806,901 greatly exceeds the likely combined resale proceeds of several depreciating luxury assets, underscoring why the cars and yacht cannot be assumed to make investors financially whole.
Luxury Spending Shaped the Public Narrative
The visual contrast between celebrity technology and conspicuous consumption gave the case a powerful public storyline, because audiences could readily distinguish between funding software development and paying for exotic automobiles, yacht work, or mansion renovations.
Recent reporting on Fritsch’s spending and fugitive status has continued to emphasize the luxury purchases, showing how tangible assets can dominate public understanding of a financial prosecution long after detailed accounting evidence leaves the courtroom.
That attention can simplify a complex record, however, because corporate fraud cases involve intent, material statements, financial timing, ownership structures, and charged wire transmissions that cannot be reduced entirely to whether a defendant appeared wealthy.
Balanced reporting must therefore acknowledge both the evidentiary importance of traced personal spending and the limitation that expensive possessions, standing alone without supporting financial evidence, do not prove that an owner intentionally deceived investors.
The jury’s split verdict reinforces caution: it convicted Fritsch on one count but acquitted him on another, showing jurors evaluated the government’s allegations separately rather than treating luxury ownership as automatic proof of every charge.
The Assets Could Not Prevent Flight
Fritsch remained free on bond after the April 2025 verdict, but federal authorities say he crossed into Mexico before a June bond-revocation hearing, leaving the seized property and other visible signs of his former Malibu lifestyle behind.
Mexican law enforcement detained him in September 2025 while he allegedly possessed false identification, but he was released under immigration reporting conditions and departed for Munich, Germany, on October 6 before his American sentencing occurred.
A federal judge later sentenced Fritsch in absentia to 15 years in prison, imposed a $35,000 fine, and ordered restitution, turning the financial-fraud defendant into a sentenced international fugitive with substantial unresolved liabilities.
The sequence demonstrates that seizing prominent assets can preserve potential value and disrupt access to property without necessarily preventing a defendant from using other resources, trusted associates, identity documents, or international transportation to leave the jurisdiction.
An examination of how authorities locate international fugitives shows why investigators may keep studying financial transactions, communications, associates, travel activity, public postings, and identity records after securing the most visible domestic assets.
What Investors Can Learn From the Spending Pattern
Private-company investors should request detailed operating budgets, periodic financial statements, bank-level verification, capitalization records, related-party disclosures, executive compensation terms, independent accounting access, and enforceable reporting rights before committing substantial capital to any offering.
They should also compare claimed development milestones with payroll, vendor contracts, software releases, customer activity, and operating expenses, looking for unexplained gaps between the amount raised and the company’s observable progress.
Large housing payments, unusual vehicle expenses, personal travel, family transfers, related-company payments, and undocumented loans deserve careful review when they appear in corporate accounts or consume capital raised for defined business objectives.
No single expenditure necessarily proves fraud, but repeated personal transactions combined with inaccurate revenue statements, nonexistent institutional backing, overstated partnerships, and continued fundraising can create a broader pattern requiring immediate independent professional investigation.
Independent verification becomes especially important when a founder’s reputation, celebrity connections, prior success, or confident presentation encourages prospective investors to rely upon personal trust instead of carefully examining original financial and contractual records.
A Financial Judgment Still Awaiting Enforcement
The vehicles and yacht were within reach of American law enforcement, but the person sentenced for the underlying fraud remains abroad, illustrating the different enforcement challenges surrounding physical property, financial judgments, and international custody.
Germany’s general restrictions on extraditing its citizens outside the European Union may complicate efforts to return Fritsch, although the warrant, prison sentence, fine, restitution order, and public fugitive designation remain active considerations if his circumstances or travel change.
The FBI has offered up to $150,000 for information leading to his arrest and conviction and believes he is residing in or near Munich, maintaining public pressure nearly a year after the in-absentia sentence.
For victims, recovery may depend upon whether investigators locate additional accounts, property, receivables, transfers, or beneficial interests beyond the assets already seized, since restitution is a legal obligation rather than a guarantee that sufficient funds will be collected.
The broader lesson extends beyond StarClub because financial fraud often becomes visible through lifestyle inflation, especially when personal acquisitions accelerate while the company repeatedly seeks new capital and fails to deliver the operational results it promised investors.
The McLaren, Rolls-Royce, yacht, and Malibu renovations became more than symbols of wealth after prosecutors linked them to investor money, making luxury consumption central to the narrative that led to Fritsch’s conviction and ongoing financial liability.